How Contractor Deposit Requirements Protect Homeowners
Contractor deposit requirements can shield your wallet from unfinished projects. Call (833)-365-8755 to connect with trusted local pros and protect your investment.
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
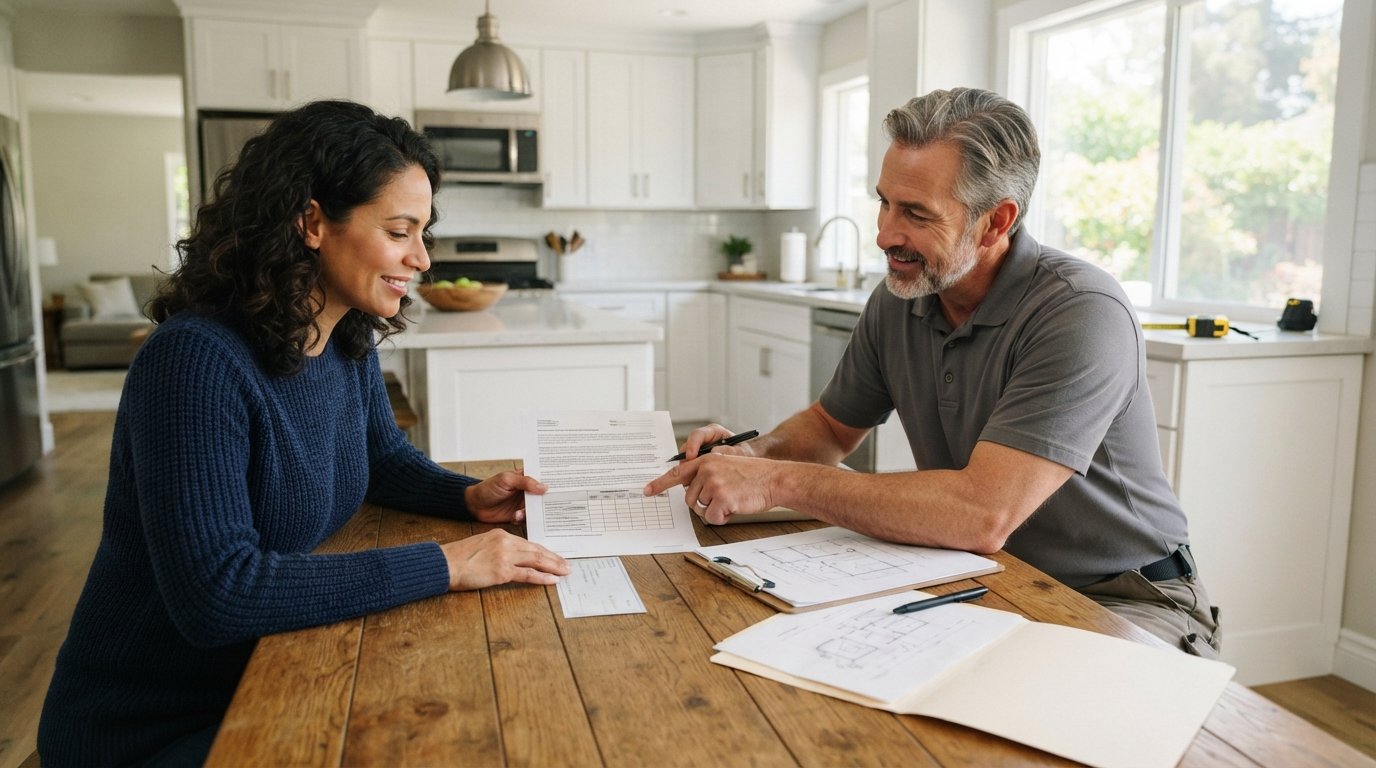
When you hand a contractor a deposit, you are not just paying for materials; you are placing trust in a stranger. That trust can feel like a gamble, especially when stories of unfinished projects and vanished contractors make headlines. But what if the deposit itself could be a shield? Contractor deposit requirements, when structured correctly, do exactly that. They create a paper trail, limit your financial exposure, and give you legal leverage if something goes wrong. Understanding these rules is not about being paranoid; it is about being prepared. This guide breaks down how deposit requirements work, what is normal, and how to use them to your advantage.
The Role of Deposits in a Healthy Contract
A deposit is more than a down payment; it is a commitment device. It signals to the contractor that you are serious, and it gives them the capital to order materials and schedule labor. But without rules, a deposit can become a trap. That is why many states regulate how much a contractor can request upfront and when they can access those funds. These regulations exist because unscrupulous operators have historically used large upfront payments to fund other projects or disappear entirely.
For homeowners, the protective power of a deposit lies in its structure. A well-structured deposit is small enough to limit your risk but large enough to secure your spot on the contractor's schedule. It is also tied to specific milestones, so the contractor earns the money as work progresses. When you understand the typical percentages and legal caps, you can negotiate from a position of knowledge rather than fear.
Typical Deposit Percentages by Trade and Project Size
There is no universal standard for deposit amounts, but industry norms vary by trade and project scope. For small repairs, such as fixing a leaky faucet or patching drywall, many contractors ask for little or nothing upfront. For larger projects like kitchen remodels or roof replacements, deposits typically range from 10% to 30% of the total contract price. Specialized trades may have their own conventions: roofers often request 10% to 20% to cover materials, while general contractors might ask for 10% to 15% to lock in scheduling.
Project size also matters. A $5,000 bathroom refresh might come with a 20% deposit ($1,000), while a $50,000 whole-home renovation might have a 10% deposit ($5,000). The key is proportionality: the larger the project, the more important it is to keep the deposit percentage low. A 30% deposit on a $100,000 project is $30,000, a sum that could be devastating to lose. By contrast, a 10% deposit on the same project is $10,000, which is still significant but easier to recover or absorb if things go wrong.
It is also worth noting that material-heavy projects, such as custom cabinetry or specialty flooring, may justify a higher deposit because the contractor must order expensive, non-returnable items early. In these cases, ask for a detailed materials list and receipts to ensure your deposit is actually being used for your project.
State Caps on Upfront Deposits and How to Check
Many states have laws that limit how much a contractor can demand upfront. For example, California caps deposits at 10% of the contract price or $1,000, whichever is less, for home improvement contracts. Other states, like Maryland and Virginia, have similar caps or require that deposits be held in escrow until work begins. These laws are designed to prevent fly-by-night operators from taking large sums and disappearing.
To find your state's rules, start with your state's consumer protection agency or contractor licensing board. Most have websites with plain-language summaries of deposit limits. You can also search for your state's home improvement contract statutes, which often specify maximum deposit amounts and required contract terms. If you are working with a licensed contractor, ask them directly about deposit requirements; a reputable professional will know the rules and be willing to explain them.
Checking these caps is not just about legal compliance; it is about setting expectations. If a contractor asks for 50% upfront in a state with a 10% cap, that is a red flag. It may indicate they are not licensed, not aware of the law, or intentionally ignoring it. In any case, you should proceed with caution and consider another contractor. For more tips on verifying a contractor's credentials, see our guide on what homeowners should verify about contractor insurance.
Payment Milestones Tied to Inspection or Completion
The most effective way to protect your deposit is to tie payments to milestones. Instead of handing over a large sum upfront, you can negotiate a schedule where the contractor receives payment only after specific phases are completed and inspected. For example, on a kitchen remodel, you might pay 10% at contract signing, 25% when demolition is complete, 25% when cabinets are installed, 25% when countertops and fixtures are in, and the final 15% after a walkthrough and punch list are finished.
This approach shifts the financial risk away from you and onto the contractor, who must complete each phase before getting paid. It also gives you regular opportunities to inspect the work and catch problems early. If a contractor resists milestone payments and insists on a large upfront deposit, that is a warning sign. Reputable contractors are usually comfortable with milestone-based payments because they know they can deliver.
When setting milestones, be specific in the contract. Use clear, objective criteria: "Demolition complete and debris removed" is better than "start of work." Include a clause that allows you to withhold payment if work is defective or incomplete. And always pay by check or credit card so you have a record of the transaction. For a step-by-step guide to planning your project and hiring the right pro, explore remodeling resources and connect with local contractors who understand these best practices.
How to Recover a Deposit if Work Never Starts
Even with precautions, there may be times when a contractor takes your deposit and never shows up. If that happens, act quickly. First, send a written demand letter via certified mail, stating that the contractor has breached the contract and demanding a full refund within a specified period (e.g., 10 business days). Keep a copy for your records. If the contractor does not respond, you have several options.
File a complaint with your state's contractor licensing board and consumer protection agency. These agencies can investigate and may suspend or revoke the contractor's license. You can also file a claim in small claims court if the amount is within your state's limit (often $5,000 to $10,000). For larger amounts, you may need to consult an attorney. If you paid by credit card, you can dispute the charge, but be aware that deadlines apply (typically 60 days from the statement date).
To strengthen your case, gather all documentation: the contract, payment receipts, emails, text messages, and photos of the work site. The more evidence you have, the better your chances of recovery. And remember, prevention is better than cure: always verify the contractor's license and insurance before paying any deposit. Our article on contractor insurance verification explains what to check.
Practical Steps to Protect Your Deposit
Now that you understand the landscape, here is a checklist to safeguard your money from the start. Following these steps can turn a deposit from a risk into a tool for accountability.
- Research local caps: Check your state's maximum deposit limit and ensure the contract complies.
- Negotiate a milestone schedule: Tie payments to completed phases, not arbitrary dates.
- Get everything in writing: The contract should specify deposit amount, payment schedule, and refund conditions.
- Pay with traceable methods: Use credit cards or checks, never cash.
- Verify credentials: Confirm the contractor's license and insurance before signing.
Following these steps does not guarantee a perfect project, but it dramatically reduces your exposure. It also signals to contractors that you are informed and expect professionalism, which often attracts better-quality professionals.
Red Flags That Undermine Deposit Protections
Even with laws and best practices, some contractors find ways to circumvent protections. Watch for these warning signs: a demand for a large cash deposit before any contract is signed, reluctance to provide a written contract, requests for payment to a personal account rather than a business account, and pressure to pay quickly. Any of these should prompt you to walk away.
Another red flag is a contractor who cannot or will not explain the deposit requirements in your state. A legitimate professional will be transparent about costs and legal obligations. If they seem evasive, consider it a sign of potential trouble. Trust your instincts: it is better to lose a deposit opportunity than to lose your entire deposit.
Final Thoughts
Contractor deposit requirements are not just bureaucratic hurdles; they are consumer protections designed to level the playing field. By understanding typical percentages, state caps, and milestone payments, you can structure your contract to keep your money safe while still getting the work done. And if something goes wrong, you have tools to recover your funds. Remember, a deposit is your leverage; use it wisely.