Home Renovation Loan Versus Contractor Financing: Which Is Better?
Compare home renovation loan versus contractor financing to find the lower-cost option and protect your project. Call (833)-365-8755 for guidance today.
By Owen Carter
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
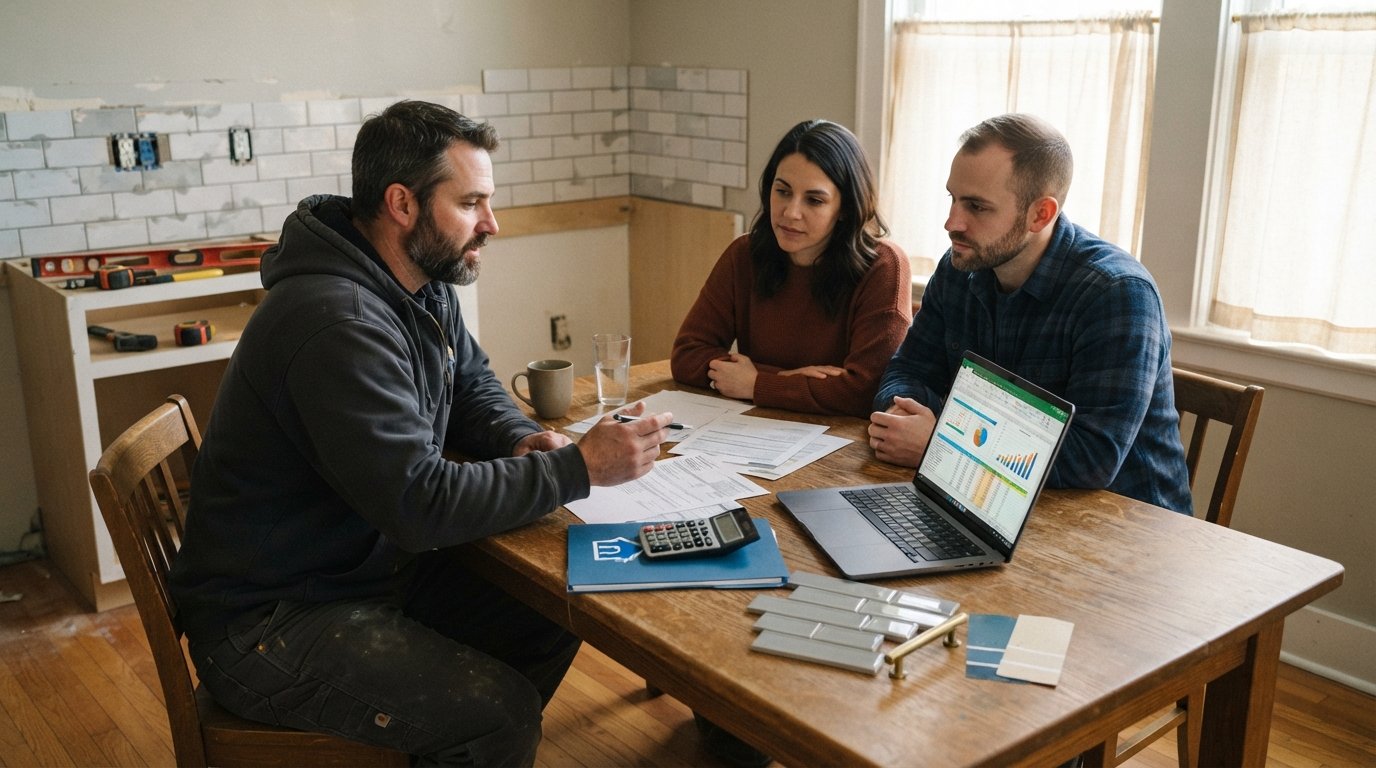
You have finally decided to remodel that outdated kitchen or add the primary suite you have been dreaming about for years. The design is set, the contractor is ready, and then comes the moment that stops many homeowners cold: how to pay for it. Two common paths emerge, and they can feel confusing when you are standing in the middle of a showroom with a clipboard. Should you walk into your bank for a home renovation loan, or should you accept the financing plan your contractor is offering at the kitchen table? The answer depends on far more than the monthly payment quoted to you on a brochure. Understanding the mechanics, risks, and true costs of each option is the difference between a smooth project and a financial headache that lingers long after the last coat of paint dries.
This comparison breaks down the home renovation loan versus contractor financing debate with the detail you need to make a confident decision. You will see how interest rates really compare, why the fine print on dealer financing deserves a second and third read, and when a home equity line of credit quietly beats both options. You will also learn how payment schedules should align with the work being completed so you never pay for a project that has not happened yet. By the end, you will have a framework for choosing the funding source that protects your wallet, your home, and your leverage with the people doing the work.
How Home Renovation Loans and Contractor Financing Actually Differ
A home renovation loan is money you borrow from a third-party lender, typically a bank, credit union, or online lender. The lender evaluates your credit, income, and debt-to-income ratio, then issues funds that you use to pay your contractor. Common forms include personal loans, home equity loans, home equity lines of credit (HELOCs), and government-backed options like FHA 203(k) or Fannie Mae HomeStyle loans for larger projects. The key characteristic is separation: the lender holds the note, and the contractor simply gets paid according to the schedule you and the lender establish.
Contractor financing, sometimes called dealer financing or in-house financing, works differently. The contractor partners with a finance company or, in some cases, extends credit directly. You apply through the contractor, often in minutes, and the contractor receives payment from the finance company while you repay the finance company over time. This convenience is real: you can sign up during the estimate appointment and start the project quickly. But the entity evaluating your application is not necessarily looking out for your long-term financial interest. The contractor wants to close the sale, and the finance partner wants to originate a loan. That dynamic shapes everything from the interest rate to the disclosures you receive.
To compare them fairly, you need to look at five dimensions: interest rate, term length, fees, lien risk, and payment timing. The table below summarizes the typical landscape, but keep reading because the details behind each row matter enormously.
- Interest rates: Personal loans often range from 6% to 36% APR depending on credit; contractor financing frequently lands in the 9% to 25% range and can go higher for promotional offers that revert to steep rates.
- Term length: Bank loans commonly run 2 to 7 years; contractor plans may stretch to 10 or 12 years, which lowers the monthly payment but increases total interest.
- Fees: Origination fees of 1% to 5% are common on personal loans; contractor financing may bury fees in the amount financed or charge prepayment penalties.
- Lien risk: Home equity loans and HELOCs place a lien on your property; personal loans are unsecured; contractor financing may involve a mechanics lien if the finance company is not paid properly.
- Payment timing: Lenders with draw schedules release funds as work is completed; contractor financing often pays the contractor upfront, which shifts risk to you.
That last point deserves emphasis. When a lender controls the purse strings through a draw schedule, the contractor has a financial incentive to complete each phase before requesting the next payment. When a contractor receives a lump sum from a finance company at signing, your leverage to ensure completion and quality diminishes. This is not to say all contractor financing is predatory, but the structure inherently favors the seller. Understanding this asymmetry is the first step toward protecting yourself.
The Real Cost of Contractor Financing: Rates, Terms, and Hidden Traps
Contractor financing advertisements often lead with a low monthly payment or a promotional rate like 0% for 12 months. These offers can be legitimate, but they come with conditions that homeowners frequently miss. The promotional rate may apply only if you pay the full balance within the promotional period; otherwise, deferred interest can retroactively apply to the entire original balance, turning a 0% offer into a 20% or 25% effective rate. The monthly payment quoted might be based on an extended term that maximizes interest for the lender. And the application process may not include the same underwriting scrutiny as a bank loan, which means you could be approved for an amount that stretches your budget further than is comfortable.
Interest rates on contractor financing vary widely because the market is less transparent than the bank loan market. A contractor might offer a plan through a third-party finance company that specializes in home improvement lending. These companies often charge higher rates than a credit union personal loan because they are taking on borrowers with a range of credit profiles and because the contractor may receive a fee for referring you. In some cases, the contractor pays a fee to the finance company, which is then passed back to you in the form of a higher project price. This is why two contractors can quote the same scope of work at different prices when financing is involved: the cost of the financing is baked into the bid.
Term length is another area where contractor financing can look attractive on the surface but cost more over time. A 12-year term on a $40,000 project at 10% APR results in total interest of roughly $23,000, compared to about $8,500 on a 5-year term at the same rate. The lower monthly payment feels manageable, but you are paying for that comfort many times over. Before signing, ask for the total of payments, not just the monthly figure. A reputable lender will provide this without hesitation; a contractor pushing an in-house plan may not volunteer it.
Finally, watch for prepayment penalties and balloon payments. Some contractor financing agreements include a penalty if you pay off the loan early, which traps you in a high-interest arrangement even if you come into money. Balloon payments, where a large lump sum comes due at the end of the term, are less common but still appear in some dealer financing structures. These features are rare in standard bank personal loans and virtually unheard of in HELOCs. If you see them in a contractor financing offer, treat them as red flags and ask for a plain-language explanation of what happens if you pay early or reach the end of the term.
Lien Risk and Disclosure: What You Are Really Signing
When you finance a renovation through a contractor, you may be signing more than a loan agreement. Depending on your state and the structure of the financing, the finance company or contractor may file a mechanics lien against your property if payments are not made according to the contract. A mechanics lien is a legal claim against your home that can cloud the title, making it difficult to sell or refinance until the lien is resolved. Even if you believe you are paying on time, a dispute between the contractor and the finance company, or a clerical error in payment processing, can trigger a lien notice that you discover only when you try to sell your home.
Disclosure requirements also differ. Bank loans and home equity products are subject to federal Truth in Lending Act disclosures that standardize how the APR, finance charge, and total of payments are presented. Contractor financing arranged through a third-party finance company is often subject to the same rules, but the presentation can be less clear because the contractor is not a lender and may not fully understand the product. Some in-house financing arrangements fall into regulatory gray areas, particularly when the contractor is not a licensed lender. You may receive less documentation, and the terms may be explained verbally rather than in writing. Verbal promises about rates or terms are nearly impossible to enforce if they are not in the contract.
There is also the matter of who holds the risk if the project goes wrong. With a lender-controlled draw schedule, you have an ally in the lender: they do not release funds for incomplete work, and they have an interest in ensuring the project progresses. With contractor financing, the finance company has already paid the contractor. If the contractor walks off the job or performs substandard work, you are still on the hook for the loan while you fight for remediation. This is a worst-case scenario, but it happens often enough that consumer protection agencies regularly warn homeowners about it. The safest approach is to insist on a payment schedule tied to completed milestones, regardless of who provides the financing. If a contractor resists this, that resistance is information you should weigh heavily.
Before signing any financing agreement, read the disclosure documents carefully and look for the following:
- The APR, not just the interest rate, so you can compare the true annual cost across offers.
- The total of payments, which tells you exactly how much the project will cost including interest.
- Whether a lien will be placed on your home and under what conditions it could be enforced.
- Prepayment penalty language and any conditions on promotional rates.
- The cancellation policy, including your right to cancel within three business days for certain home improvement contracts.
If any of these items are missing or unclear, ask for them in writing before you sign. A legitimate lender or contractor will provide them without pressure. If you feel rushed, that is a sign to slow down.
When a HELOC or Personal Loan Is the Cheaper Path
For many homeowners, a home equity line of credit or a personal loan from a bank or credit union beats contractor financing on both cost and control. A HELOC uses the equity in your home as collateral, which allows lenders to offer lower interest rates than unsecured products. Rates on HELOCs are often tied to the prime rate and can be variable, but even with adjustments they frequently undercut contractor financing by several percentage points. You can draw funds as needed, which aligns naturally with a phased renovation, and you pay interest only on what you draw during the draw period. This flexibility is valuable for projects where the scope may evolve.
Personal loans are unsecured, meaning they do not put your home on the line. Rates are higher than HELOCs but still often lower than contractor financing, especially if you have good credit. The application process is straightforward, funds arrive quickly, and you can use the money with any contractor you choose. That last point matters: when you bring your own financing, you preserve your ability to walk away from a contractor whose bid or terms do not satisfy you. You are not tied to a contractor because they offered a convenient payment plan. For a deeper look at how these options stack up, see our guide on home renovation financing options compared: loans and credit lines, which walks through the tradeoffs in detail.
Government-backed renovation loans deserve consideration for larger projects or older homes. An FHA 203(k) loan allows you to finance the purchase or refinance of a home plus renovation costs in a single mortgage, which can be useful if you are buying a fixer-upper. Fannie Mae's HomeStyle loan serves a similar purpose for conventional borrowers. These products require approved contractors and inspections, which adds paperwork but also adds protection. The interest rate is tied to your mortgage, so it is typically lower than any personal loan or contractor financing, and the term can stretch to 30 years. The tradeoff is complexity and a longer timeline to close.
Here is a simple decision framework for comparing costs:
- Gather quotes from at least two lenders: your bank, a credit union, and an online lender. Ask for the APR and total of payments on the amount you need.
- Ask the contractor for the total project cost with and without their financing. The difference is the effective cost of their financing.
- Compare the total cost of each option over the expected repayment period, not just the monthly payment.
- Factor in the value of control: lender financing with a draw schedule gives you leverage; contractor financing may not.
- Choose the option with the lowest total cost that preserves your ability to manage the contractor and the project.
In most cases, a HELOC or a personal loan from a reputable lender will win on total cost. The exception is when you have poor credit and cannot qualify for a competitive bank product, in which case contractor financing may be the only available path. Even then, read the terms with extra care and consider whether a smaller project or a delay to improve your credit score is the wiser move.
Payment Schedules and Draws: Aligning Money With Work
The structure of payments is where the home renovation loan versus contractor financing comparison becomes practical rather than theoretical. With a lender-managed draw schedule, funds are released in stages as work is completed and inspected. A typical schedule might release 10% at contract signing, 25% at rough framing, 25% at mechanical rough-in, 25% at drywall completion, and the remainder at final inspection. The lender or a third-party inspector verifies progress before each release. This protects you because the contractor cannot collect the full project amount before completing the work. It also protects the contractor because they know funds are available and will be released on a predictable schedule.
Contractor financing often inverts this structure. The finance company pays the contractor a lump sum shortly after the loan is originated, sometimes within days of signing. The contractor now has the money, and you have a monthly payment. If the contractor is reputable and the project is well managed, this works fine. But if the contractor encounters financial difficulty, takes on too many projects, or simply deprioritizes your job, you have limited recourse. You can sue for breach of contract, but that takes time and money, and the loan payments continue regardless. This is why consumer advocates recommend never paying more than a small deposit upfront, regardless of the financing source.
If you do choose contractor financing, negotiate a payment schedule that ties disbursements to milestones, even if the finance company pays the contractor directly. Ask the contractor to provide a written schedule showing when they will receive funds from the finance company and how those receipts correspond to project phases. Request that the finance company release funds in stages rather than a lump sum. Some finance companies accommodate this; others do not. If they will not, that is a signal about how much control you will have over the project timeline. You can also ask your contractor to connect you with a reputable local professional through a service like HomeRemodelingsContractors, which helps homeowners plan affordable projects and compare estimates from experienced contractors, so you can start the financing conversation with a clear scope and a vetted pro.
One more consideration: retainage. Many construction contracts include a retainage clause, typically 5% to 10% of the contract price, withheld until final completion and punch-list items are resolved. This gives you leverage to ensure the contractor returns to fix minor issues. Lender draw schedules often build in a final payment that functions as retainage. Contractor financing may not. If you are using contractor financing, insist on a retainage clause in the construction contract itself, separate from the financing agreement. This is your best protection against a contractor who disappears after the bulk of the work is done.
Making the Decision: A Practical Checklist
The right choice depends on your financial situation, your credit profile, the size of the project, and your tolerance for risk. Before you commit to either path, run through a structured evaluation. Start by getting pre-approved for a personal loan or HELOC so you know your borrowing power and the rate you qualify for. This gives you a baseline against which to measure any contractor financing offer. Then ask each contractor you interview whether they offer financing and, if so, request the full terms in writing. Compare the APR and total of payments on the contractor's offer to your pre-approved bank offer. If the contractor's rate is higher, ask whether they will reduce the project price to match the bank financing, since they are saving on finance fees.
Consider the timeline of your project and how it affects your financing choice. A short, simple project like a bathroom refresh may be well suited to a personal loan with a 3-to-5-year term. A larger, phased renovation may benefit from a HELOC that you can draw on as needed. A major structural project or an older home with significant unknowns may warrant a government-backed renovation loan with inspections built in. Contractor financing can be convenient for smaller projects where the rate difference is modest and the contractor is highly reputable, but it should rarely be the default choice for large projects where the stakes are high.
Finally, protect yourself regardless of the path you choose. Get everything in writing, including the scope of work, the payment schedule, the financing terms, and the dispute resolution process. Do not sign a contract with blank spaces or vague language. Verify that your contractor is licensed and insured in your state, and ask for references from recent projects of similar size. A good contractor will welcome these questions; a bad one will resist them. The financing decision is important, but it is only one part of a successful renovation. The contractor you hire matters just as much as the loan you choose, and the two decisions should be made together with clear eyes and a full understanding of the costs and risks involved.
Take the time to compare offers side by side, ask hard questions, and prioritize total cost and control over monthly payment convenience. Your future self, the one enjoying the finished space without a lingering financial burden, will thank you for the diligence.