Does My Contractor Need Insurance: What Homeowners Verify
Does my contractor need insurance and what should homeowners verify? Call 8333658755 to connect with vetted local pros and protect your remodel investment.
By Oliver Grant
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Hiring a contractor for a kitchen remodel, roof replacement, or bathroom update is a significant financial commitment. Before you sign a contract or hand over a deposit, you need to answer a critical question: does my contractor need insurance and what should homeowners verify? The short answer is yes, and the details matter more than most people realize. A contractor without proper coverage can leave you paying for injuries, property damage, and unfinished work out of your own pocket.
This guide walks you through the specific types of insurance every contractor should carry, how to verify each policy, and the red flags that signal you should walk away. You will also learn how to protect yourself when a contractor cannot provide proof of coverage and what questions to ask before work begins.
Why Contractor Insurance Matters for Your Home and Wallet
When a contractor steps onto your property, they bring workers, tools, vehicles, and potential liability. If a worker falls off a ladder while installing your new roof, who pays the medical bills? Without workers compensation insurance, that responsibility can shift to you as the homeowner. If a contractor accidentally breaks a water line and floods your basement, their general liability policy should cover the damage. Without it, you may be filing a claim with your own homeowners insurance, which can raise your premiums or result in a denial.
The financial exposure is real. A single serious injury on your property can result in medical costs exceeding $100,000. Property damage from a careless mistake can run into tens of thousands of dollars. Most homeowners do not have that kind of cash sitting in a savings account, and their homeowners policy may not cover contractor negligence. This is why verifying insurance before work begins is not optional. It is one of the most important steps in protecting your home and your finances.
Beyond the financial risk, hiring an uninsured contractor often means hiring someone who cuts corners. Contractors who skip insurance may also skip permits, use substandard materials, or disappear before the job is finished. The insurance question is a proxy for professionalism. A contractor who carries proper coverage is more likely to run a legitimate business, follow building codes, and stand behind their work.
The Two Essential Policies Every Contractor Should Carry
Not all contractor insurance is the same. Two policies form the foundation of proper coverage: general liability insurance and workers compensation insurance. Each one protects you in different ways, and you should verify both before any work begins.
General liability insurance covers third-party claims for bodily injury and property damage. If a contractor damages your neighbor's fence while backing a truck into your driveway, this policy responds. If a visitor trips over a cord the contractor left across your walkway, general liability covers the claim. Most general contractors carry between $500,000 and $2 million in general liability coverage. The exact amount depends on the size of their business and the type of work they perform.
Workers compensation insurance covers medical expenses and lost wages for employees injured on the job. In most states, contractors with employees are legally required to carry this coverage. If a worker gets hurt on your property and the contractor does not have workers compensation, the injured worker may sue you directly. Even if you win the lawsuit, legal fees can be devastating. Some states also allow injured workers to file claims against the homeowner's insurance policy, which can lead to premium increases or policy cancellation.
Here is a quick breakdown of what each policy protects against:
- General liability: third-party injuries, property damage to others, and certain completed-operations claims
- Workers compensation: employee injuries, medical bills, rehabilitation, and lost wages
- Commercial auto: accidents involving company vehicles while traveling to and from your job site
- Umbrella or excess liability: additional coverage beyond the base policy limits for catastrophic claims
Some contractors also carry builder's risk insurance, which covers the structure itself during a renovation. This is especially common on large projects where the home is exposed to the elements or unoccupied for extended periods. Builder's risk is not always required, but it is a valuable layer of protection on major remodels.
How to Verify Contractor Insurance Step by Step
Asking a contractor if they have insurance is not enough. Anyone can say yes. You need to see proof, and you need to confirm that the policy is active and covers the work being performed. Follow these steps to verify coverage properly.
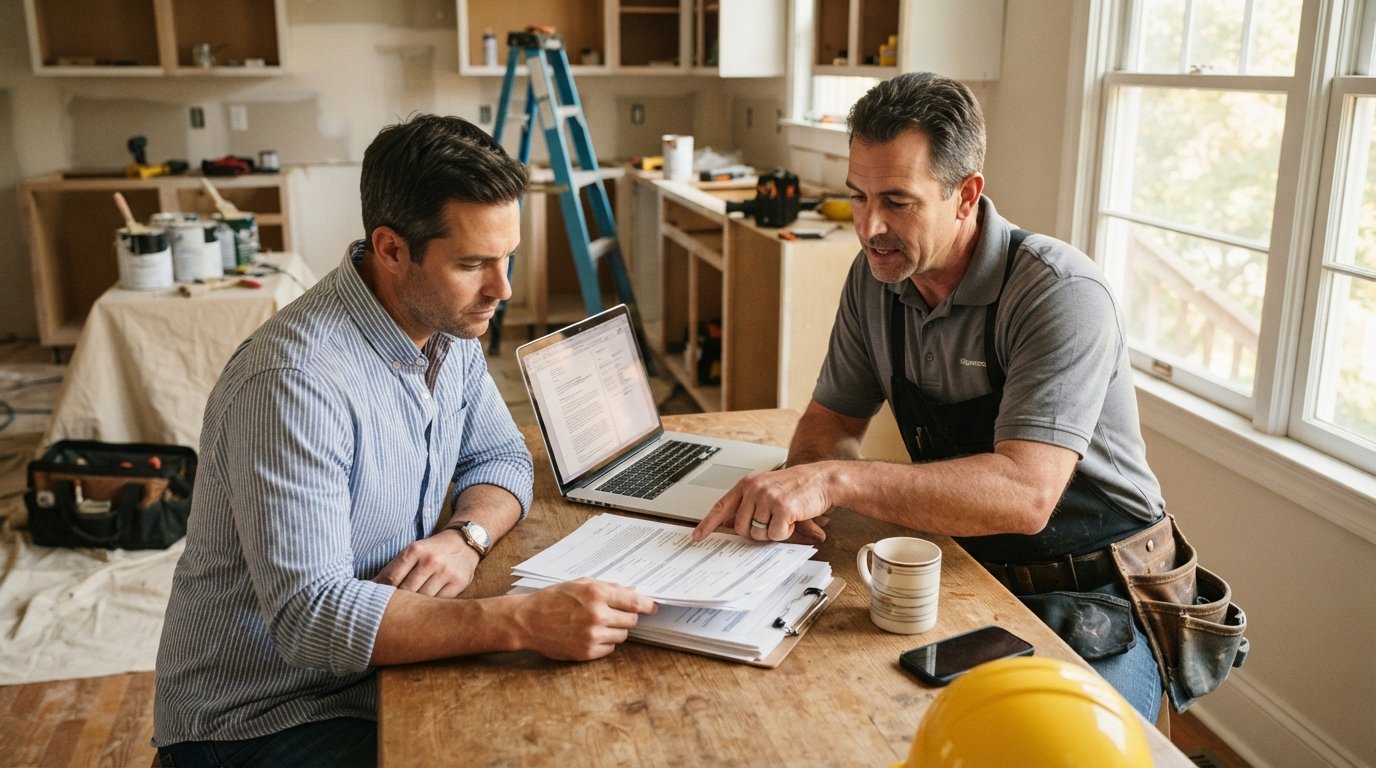
- Request a certificate of insurance. Ask the contractor to provide a COI from their insurance carrier. The certificate should list the policy number, coverage limits, effective dates, and the insurance company's contact information.
- Call the insurance company directly. Use the phone number on the certificate to confirm the policy is active. Do not rely solely on the document, which can be altered or expired.
- Check that the policy covers the specific work. A roofer's policy may exclude certain high-risk tasks. Ask the insurer if the policy covers the type of project you are hiring for.
- Verify workers compensation separately. General liability does not cover employee injuries. Ask for a separate certificate for workers compensation and confirm it is active.
- Ask about subcontractors. If the contractor plans to hire subcontractors, ask whether those subcontractors carry their own insurance. Some general contractors require subcontractors to provide certificates before starting work.
If a contractor hesitates to provide documentation or pressures you to skip this step, treat that as a serious warning sign. Legitimate contractors expect homeowners to verify insurance. They keep certificates on hand and can provide them quickly. A contractor who cannot or will not provide proof is not worth the risk.
For homeowners planning larger projects, such as a full kitchen renovation, understanding the timeline and insurance requirements can help you coordinate with your contractor more effectively. Our guide on how long a kitchen remodel takes explains what to expect at each stage, including when to verify insurance and permits.
What Happens When Your Contractor Is Not Insured
The consequences of hiring an uninsured contractor can be severe and long-lasting. Imagine a worker falls from your roof while replacing shingles. Without workers compensation, the worker may file a claim against your homeowners insurance. Your insurer may pay the claim, but your premiums could increase by hundreds or thousands of dollars per year. In some cases, the insurer may deny the claim entirely if it determines you were negligent in hiring an uninsured contractor.
Property damage is another risk. If an uninsured contractor accidentally breaks a window, damages your siding, or causes a water leak that ruins drywall, you may have to pay for repairs yourself. Your homeowners policy might cover the damage, but you will likely face a deductible and a premium increase. If the damage is extensive, your insurer could cancel your policy altogether.
There is also the risk of unfinished work. An uninsured contractor may lack the financial stability to complete your project. If they walk away mid-job, you are left with a half-finished renovation and no recourse. You may need to hire a second contractor to fix the mess, doubling your costs and extending your timeline.
Finally, hiring an uninsured contractor can affect your ability to sell your home. If you pull permits for a renovation, the work must pass inspection. Unpermitted or improperly completed work can create title issues and scare off buyers. Even if you do not pull permits, a home inspector may flag shoddy work during a pre-sale inspection, forcing you to make repairs before closing.
Bonding, Licensing, and Other Credentials to Check
Insurance is essential, but it is not the only credential you should verify. Depending on your state and the type of work, your contractor may also need a license and a bond. A license demonstrates that the contractor has met state requirements for training and experience. A bond provides a financial guarantee that the contractor will complete the work according to code and pay for any damages they cause.
To check a contractor's license, visit your state's licensing board website. Most states allow you to search by name or license number. The search results should show the license status, expiration date, and any disciplinary actions. If a contractor claims to be licensed but cannot be found in the state database, that is a major red flag.
Bonding is separate from insurance. A surety bond is a three-party agreement between the contractor, the bonding company, and the homeowner. If the contractor fails to complete the work or violates building codes, the homeowner can file a claim against the bond. Not all states require contractors to be bonded, but many do for certain trades and project sizes. Ask your contractor for proof of bonding and verify it with the bonding company.
When you connect with contractors through a platform like HomeRemodelingsContractors.com, you can ask about insurance, licensing, and bonding upfront. The platform helps homeowners plan affordable projects and connect with experienced local contractors, making it easier to compare options and move forward with confidence.
Red Flags That Signal an Uninsured or Unreliable Contractor
Even if a contractor provides a certificate of insurance, other warning signs can indicate deeper problems. Pay attention to how they communicate, how they handle paperwork, and how they respond to your questions. The following red flags should prompt you to slow down or walk away entirely.
- They ask for a large cash deposit upfront, before any work begins.
- They refuse to provide a written contract or scope of work.
- They cannot provide a certificate of insurance or give excuses for why they do not have one.
- They pressure you to skip permits or say permits are not necessary for your project.
- They have no physical business address or only provide a P.O. box.
- They ask you to make the check out to a person rather than a business name.
Any one of these behaviors is concerning. Two or more together should be a dealbreaker. Remember that you are inviting this person into your home and trusting them with a significant investment. If they cannot demonstrate professionalism during the hiring process, they are unlikely to demonstrate it during construction.
It is also worth checking online reviews and asking for references from recent clients. A contractor with a history of disputes, lawsuits, or unresolved complaints is not worth the risk, even if they carry insurance. Insurance protects you in a worst-case scenario, but you would rather avoid the worst-case scenario altogether.
Questions to Ask Before You Sign Anything
Before you commit to a contractor, ask a consistent set of questions. These questions help you compare contractors fairly and ensure that you are making an informed decision. Write down the answers and keep them with your project records.
- What is your license number, and can I verify it with the state?
- Can you provide a certificate of insurance for general liability and workers compensation?
- Will you use subcontractors, and are they insured?
- Who will pull the permits, and will the work be inspected?
- What is the payment schedule, and how much is due upfront?
- What is the estimated timeline, and how will you communicate delays?
- What warranty do you offer on labor and materials?
If a contractor cannot answer these questions clearly, that is a sign they may not have the experience or systems in place to manage your project. A professional contractor will appreciate your diligence and provide straightforward answers. They know that informed homeowners are easier to work with and that a clear agreement protects both parties.
Once you have verified insurance, licensing, and references, put everything in writing. Your contract should include the scope of work, materials, timeline, payment schedule, and warranty terms. It should also include a clause requiring the contractor to maintain insurance throughout the project. If the contractor's policy lapses mid-job, you want the right to pause work until coverage is restored.
Protecting Yourself When Insurance Falls Short
Even with proper insurance, problems can arise. A contractor's policy may have limits that are too low to cover a catastrophic event. The insurer may dispute a claim. The contractor may fail to pay subcontractors, leading to mechanics liens against your home. These scenarios are rare, but they are worth preparing for.
One way to protect yourself is to request a waiver of subrogation from the contractor's insurer. This prevents the insurer from pursuing you for damages after paying a claim. Another option is to require the contractor to name you as an additional insured on their general liability policy. This gives you direct access to coverage if you are sued for something related to the contractor's work.
You can also hold back a portion of the final payment until the project passes inspection and all subcontractors and suppliers have been paid. This is called a retainage, and it gives you leverage if problems arise after the work is complete. The specific amount and timing should be spelled out in your contract.
Finally, keep detailed records throughout the project. Save copies of the contract, change orders, receipts, certificates of insurance, and correspondence with the contractor. If a dispute arises, these records will help you resolve it quickly and fairly. They also demonstrate that you acted in good faith and took reasonable steps to protect your home.
Hiring a contractor is a partnership, and insurance is one of the most important ways to protect that partnership. By verifying coverage before work begins, you reduce your risk, protect your finances, and increase the odds that your project will be completed on time and on budget. Take the extra time to ask the right questions and confirm the answers. Your future self will thank you.