How to Read a Home Renovation Contract Before Signing
Learning how to read a home renovation contract before signing helps you avoid surprise bills and protect your deposit. Call (833)-365-8755 for guidance.
By Amelia Reed
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
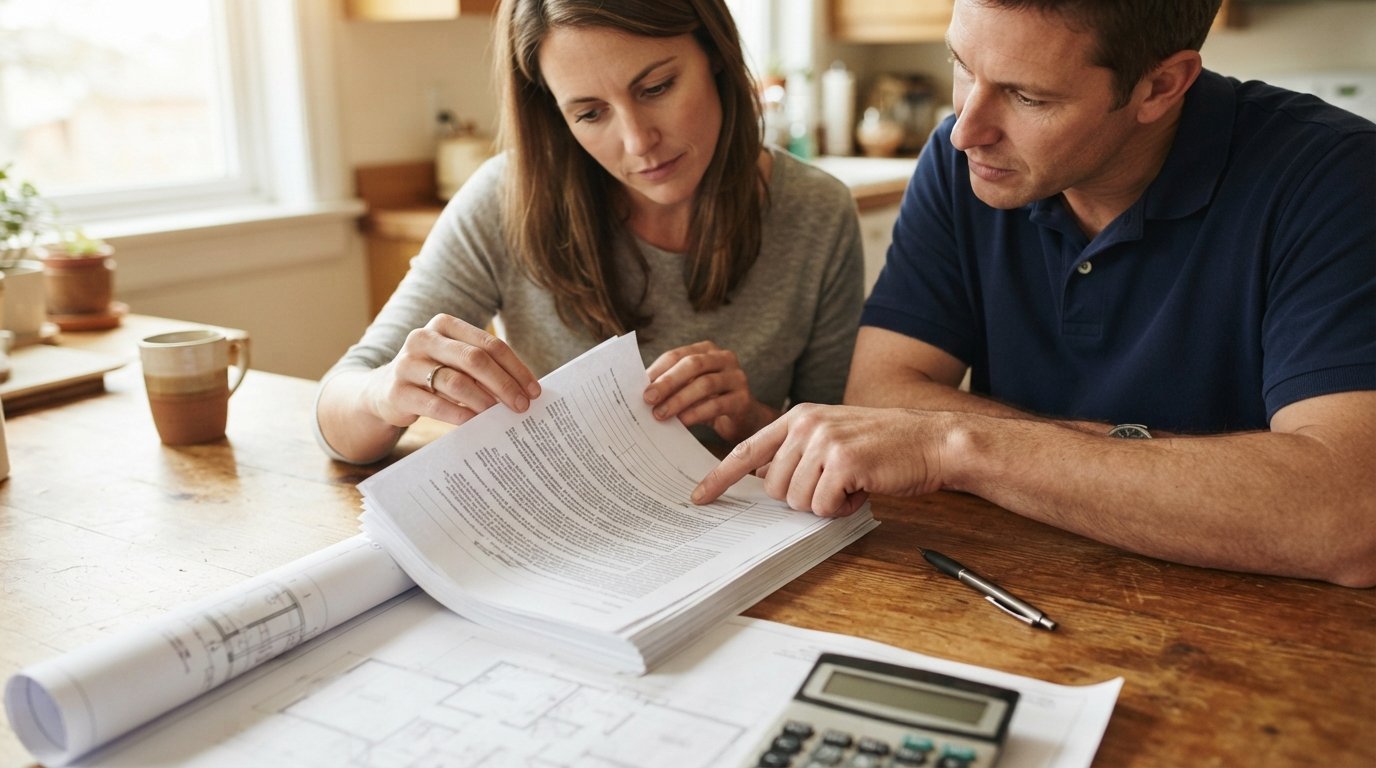
You have spent weeks comparing bids, checking references, and imagining the finished space. The contractor slides a multi-page agreement across the table and asks for a signature. In that moment, most homeowners feel a mix of excitement and pressure to just get started. That is exactly when costly mistakes happen. A renovation contract is not a formality; it is the legal blueprint for your project, your money, and your recourse if things go wrong. Learning how to read a home renovation contract before signing is one of the highest-return skills you can develop as a homeowner. This guide walks through the clauses that matter most, the language that should raise a red flag, and the questions to ask before you pick up a pen.
Start With the Scope of Work, Allowances, and Exclusions
The scope of work section defines what the contractor will actually do. Vague language here is the root of most renovation disputes. A line item that says "install flooring" tells you almost nothing. Which rooms? What material? Who moves the furniture? Is subfloor repair included? A well-written scope specifies materials by brand, model, and quantity, describes the workmanship standard, and lists every room or area affected. If you cannot picture exactly what you are buying, the contract is not finished.
Allowances deserve special attention. Many contracts include an allowance, which is a budget line for items the homeowner has not selected yet, such as tile, fixtures, or lighting. The contract should state the allowance amount and, critically, what happens if your selections exceed it. A common trap is a low allowance that forces you into expensive change orders later. Ask the contractor to explain how overages are priced and whether you pay the difference at cost or with a markup. Also look for a list of exclusions, which are tasks the contractor will not perform. Permits, debris removal, painting, and final cleaning are frequently excluded by default. Knowing what is left out lets you budget for those items or negotiate them into the deal.
Before you compare contracts, it helps to understand the broader planning sequence, because a strong scope flows from a solid plan. Our guide on home renovation planning steps to avoid costly mistakes explains how to define priorities and budgets before you ever request bids. When you bring that clarity to the contract table, you can spot gaps in the scope quickly and ask better questions.
Examine the Payment Schedule and Change Order Clause
The payment schedule dictates when your money leaves your account, and it should track progress, not the calendar. A fair schedule might look like a modest deposit (often 10 to 20 percent), a payment at rough framing or demolition completion, a payment at substantial completion of major systems, and a final payment after a walkthrough and punch list. Be cautious of contracts that demand large sums upfront or ask for the majority of the money before work begins. That structure reduces the contractor's incentive to finish and leaves you with little leverage if problems arise.
Equally important is the change order clause. Renovations almost always involve changes, whether from hidden damage, design shifts, or material delays. A good change order clause requires written approval, a fixed price, and a schedule impact statement before any extra work begins. Verbal approvals are a recipe for invoice surprises. The contract should also explain how change orders affect the payment schedule and the completion date. If the clause is missing or vague, ask for it in writing.
Cancellation rights are another area homeowners overlook. Depending on your state, you may have a cooling-off period for certain contracts, often three business days for door-to-door sales or emergency repairs. The contract should state your cancellation rights clearly, including how to cancel and what refund you are entitled to. Federal Trade Commission rules also require a three-day cancellation window for many home solicitation sales. If the contract is silent on cancellation, ask the contractor to add a clause that reflects your state's requirements.
- Deposit: keep it low, ideally 10 to 20 percent, and tie it to mobilization costs.
- Progress payments: tie each one to a measurable milestone, not a date.
- Final payment: hold back enough to cover punch list items, often 5 to 10 percent.
- Change orders: require written approval and a fixed price before work starts.
- Cancellation: confirm your state's cooling-off period and get it in the contract.
When these terms are clear, you protect your cash flow and keep the project moving on your terms. A contractor who resists a milestone-based schedule is telling you something about how they manage money and risk.
Check Lien Waivers and Proof of Insurance
Mechanic's liens are a legal tool that allows contractors, subcontractors, and suppliers to claim an interest in your property if they are not paid. Even if you pay the general contractor in full, a subcontractor who was not paid can file a lien against your home. That is why lien waiver language matters. The contract should require the contractor to provide conditional lien waivers with each payment and a final unconditional lien waiver at the end of the project. These documents confirm that parties have been paid and waive their right to file a lien.
Insurance is the other half of risk management. Ask for a certificate of insurance showing general liability coverage and workers' compensation coverage. General liability protects you if the contractor damages your home or a neighbor's property. Workers' compensation protects you if a worker is injured on your property; without it, you could face a claim. The certificate should name you as an additional insured if possible, and it should come directly from the insurer, not from the contractor's own files. Verify the policy is active by calling the insurer or checking the certificate's date.
Bonding is a related safeguard. A surety bond provides another layer of protection if the contractor fails to complete the work or violates the contract. Not every state requires bonding for residential contractors, but if your contractor is bonded, ask for proof. When you review these documents, keep copies for your records and confirm that the names on the insurance and bond match the legal entity you are contracting with, not a trade name that differs from the license.
Understand Completion Dates and Delay Penalties
Time is money in a renovation. A contract without a clear completion date gives the contractor little incentive to finish on schedule. Look for a specific start date and a substantial completion date, which is the point at which the work is complete enough for you to use the space. The contract should also define what counts as a delay. Weather, material backorders, permit delays, and homeowner-caused changes are common excuses, and some are legitimate. The key is whether the contract lists which delays excuse the contractor from the schedule and which do not.
Liquidated damages are a clause that sets a fixed amount the contractor owes you for each day of unexcused delay. This is not a penalty in the legal sense; it is a pre-agreed estimate of your loss, such as temporary housing costs or lost rental income. Not every contractor will accept a liquidated damages clause, especially on small jobs, but on large projects it is worth negotiating. If the contractor refuses, ask for a schedule with milestone dates and a written commitment to communicate delays promptly. Even without damages, a documented schedule gives you leverage and a paper trail.
Also review the suspension and termination clauses. These explain when the contractor can stop work (for example, if you fail to pay) and when you can terminate the agreement (for example, if the contractor abandons the project or performs defective work). A termination clause should describe the notice required and how unfinished work and payments are handled. Without it, ending a bad relationship can become a legal battle.
Compare Warranty Terms With Manufacturer Warranties
Warranties come from two sources: the contractor and the manufacturer. The contractor's warranty covers workmanship, such as installation errors, leaks, or uneven surfaces. The manufacturer's warranty covers defects in the product itself, such as a failing appliance or a roofing shingle that cracks prematurely. A good contract separates these two and states the duration and scope of each. Workmanship warranties often run one to two years, while manufacturer warranties can range from one year to a lifetime, depending on the product.
Read the warranty language for exclusions. Many workmanship warranties exclude damage caused by homeowner misuse, lack of maintenance, or acts of nature. Manufacturer warranties may be void if the product was installed incorrectly or by an unlicensed installer. The contract should state who handles warranty claims, how you submit a claim, and how long the contractor has to respond. If the contractor offers a warranty, get it in writing and confirm it transfers if you sell the home. Verbal promises are not enforceable.
Finally, review the dispute resolution clause. Some contracts require mediation or arbitration before litigation, and some specify the venue and which state's law applies. Arbitration can be faster and cheaper than court, but it may limit your ability to appeal. Understand what you are agreeing to before you sign. If the clause feels one-sided, ask for a mutual agreement that gives both parties the same options.
Practical Steps Before You Sign
Reading a contract is not a passive act. Treat it like a checklist and work through it systematically. Start by confirming that the legal names, license numbers, addresses, and contact information are correct. Then read the scope, payment schedule, and change order clause line by line. Highlight anything you do not understand and ask the contractor to explain it in plain language. A reputable professional will welcome the questions.
Next, verify the contractor's license and insurance through your state licensing board and the insurer. Ask for lien waivers and a certificate of insurance before work begins. Confirm the start and completion dates, the delay provisions, and the warranty terms. If the contract references attachments, such as drawings, specifications, or a schedule, make sure those documents are attached and labeled. Finally, consider having a construction attorney review the contract if the project is large or the language is complex. The cost of a review is small compared with the cost of a dispute.
If you are still narrowing down your list of professionals, HomeRemodelingsContractors.com helps homeowners plan affordable home improvement projects and connect with experienced local contractors. Their network covers remodeling, repairs, upgrades, and free estimates, so you can compare options and move forward with confidence. A vetted contractor is more likely to present a clear, fair contract from the start.
Signing a renovation contract should feel like a confident step, not a gamble. When you know how to read a home renovation contract before signing, you can spot vague scope language, unfair payment terms, missing insurance, and weak warranties before they become expensive problems. Take your time, ask questions, and get everything in writing. The finished project is worth the extra hour at the table.
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.