How to Budget for a Kitchen Remodel with a Realistic Contingency
A realistic contingency is the key to a stress-free kitchen remodel. Learn how to budget for a kitchen remodel with a realistic contingency and avoid surprise bills.
By Zoe Harper
Learn more about Kitchen Remodel for guides, costs, and what to expect.
Compare Kitchen Remodel Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
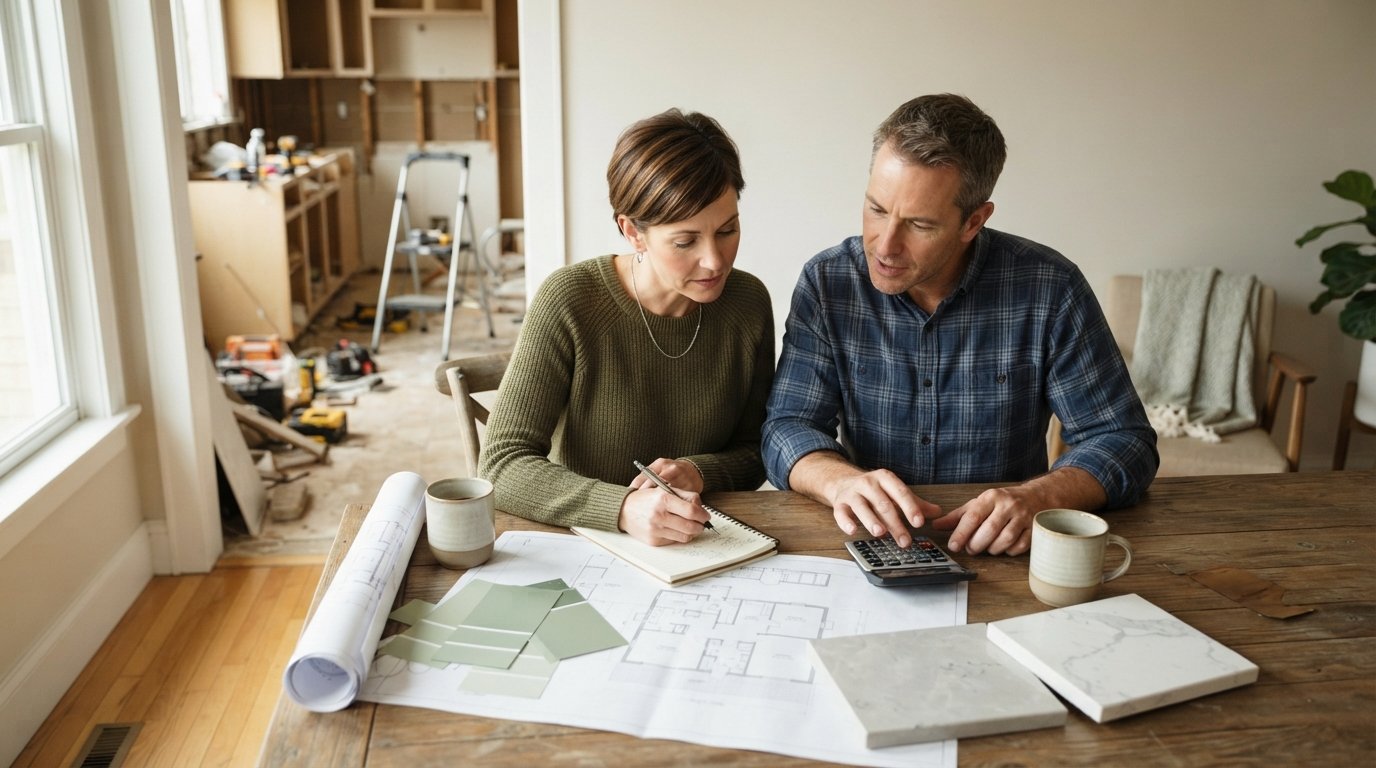
You have picked out the quartz countertops, the soft-close drawers, and the perfect shade of sage green for the walls. Then the first contractor hands you a quote that is higher than your entire savings account. Kitchen remodeling has a way of turning excitement into sticker shock, especially when the final bill creeps past the original estimate. The difference between a smooth renovation and a financial headache usually comes down to one thing: how well you planned for the unexpected. Learning how to budget for a kitchen remodel with a realistic contingency is not about pessimism. It is about protecting your project, your home, and your peace of mind.
Most homeowners start with a target number and then reverse-engineer the project to fit it. That approach often fails because it ignores the hidden costs that surface once walls come down. A better method is to build your budget from the bottom up, assign a meaningful cushion for surprises, and track every dollar as work progresses. This guide walks through that process step by step, with practical numbers and frameworks you can apply to your own kitchen.
Start with a Realistic Total, Not a Wishful Number
Before you can set a contingency, you need an honest baseline. Kitchen remodels in the United States typically fall into three broad tiers, and understanding where your project lands helps you avoid underpricing the work. A minor cosmetic refresh (paint, hardware, new faucet) might run $5,000 to $15,000. A mid-range remodel that replaces cabinets, counters, and appliances often lands between $25,000 and $75,000. A major remodel with layout changes, structural work, and high-end finishes can easily exceed $100,000.
These ranges vary by region, home age, and material choices, so treat them as starting points rather than fixed prices. The key is to gather at least three written estimates from local professionals. When you compare quotes, look beyond the bottom line. Ask what is included, what is excluded, and how the contractor handles changes. A quote that seems low often omits permits, demolition, or disposal fees, which later appear as surprise line items.
If you are unsure where to begin, a service like HomeRemodelingsContractors can connect you with experienced local contractors who provide free estimates and help you understand typical costs in your area. Getting multiple perspectives early prevents you from anchoring your budget to a single, possibly unrealistic, number.
Break the Budget into Fixed and Variable Costs
Once you have a working total, divide it into categories. Fixed costs are expenses that rarely change once the contract is signed: labor, permits, and major materials like cabinets and countertops. Variable costs are the ones that tend to drift: fixtures, lighting, backsplash tile, and any custom work. Knowing which is which helps you decide where to cut if money gets tight.
A typical kitchen remodel budget might look like this:
- Cabinets and hardware: 25 to 40 percent of the total
- Labor and installation: 20 to 30 percent
- Countertops: 10 to 15 percent
- Appliances: 10 to 20 percent
- Flooring, lighting, and plumbing fixtures: 10 to 15 percent
- Permits, design, and contingency: 10 to 20 percent
These percentages shift depending on scope. A project that moves plumbing or adds an island will push labor and permit costs higher. A cosmetic refresh will skew toward materials. The important takeaway is that contingency should be a line item from day one, not an afterthought. If you are looking for ways to trim costs without making the kitchen look cheap, our guide on how to lower kitchen remodel cost without a cheap look offers practical strategies that preserve quality.
Why a Realistic Contingency Is Non-Negotiable
A contingency is not extra money for upgrades. It is a reserve for the unknown. In remodeling, the unknown is almost guaranteed. Behind the drywall you might find outdated wiring, water damage, or plumbing that does not meet current code. These issues are not the contractor's fault, and they are rarely covered by the original quote. Without a cushion, you are forced to pause the project, borrow money, or cut corners.
The size of your contingency should reflect the age and condition of your home, the complexity of the project, and your risk tolerance. As a rule of thumb, allocate 15 to 20 percent of your total budget for a mid-range remodel in a home that is more than 20 years old. For a simple cosmetic update in a newer home, 10 percent may be sufficient. For a major remodel with structural changes, 25 percent is not unreasonable.
Consider this example. You budget $50,000 for a mid-range kitchen remodel. A 20 percent contingency adds $10,000, bringing your working total to $60,000. If the project finishes without major surprises, you can apply the leftover funds to a desired upgrade or return them to savings. If the plumbing fails inspection and needs replacement, you have the cash on hand to fix it without derailing the timeline.
How to Calculate Your Contingency Step by Step
Calculating a realistic contingency is not guesswork. It is a structured process that accounts for the specific risks in your project. Follow these steps to arrive at a number you can defend.
- Estimate the base project cost. Use your contractor quotes and material research to establish a realistic total for the work you want done.
- Assess your home's risk factors. Older homes, previous DIY work, and any history of leaks or pests increase the likelihood of hidden problems.
- Choose a percentage. Apply 10 percent for low-risk cosmetic projects, 15 to 20 percent for standard remodels, and 25 percent or more for complex or structural work.
- Add the contingency to your budget. Treat it as a separate line item so you are not tempted to spend it on finishes.
- Review and adjust. As the project progresses, revisit the contingency. If no issues arise by the midpoint, you may reallocate a portion, but keep a reserve until final inspection.
This framework works because it forces you to think about risk before you are in the middle of demolition. It also gives you a clear answer when a contractor asks about your budget range. You can say, "My working total is X, with a contingency of Y," which signals that you are prepared and serious.
Track Spending and Communicate with Your Contractor
A budget is only useful if you monitor it. Create a simple spreadsheet or use a budgeting app to log every expense, from the deposit to the final paint touch-up. Compare actual costs to your estimates weekly. If you notice a category trending over, address it immediately rather than waiting until the end.
Communication with your contractor is equally important. Ask for a written change order whenever the scope of work shifts. A change order should detail the additional work, the cost, and the impact on the timeline. Verbal agreements lead to disputes. A professional contractor will welcome this documentation because it protects both parties.
If you are working with a platform like BuySellRemodel, you can request free estimates and compare contractors side by side. This transparency helps you choose a professional who is comfortable discussing budgets and contingencies openly. The goal is a partnership, not an adversarial relationship.
Common Mistakes That Blow Up Kitchen Budgets
Even well-intentioned homeowners fall into traps that inflate costs. Knowing them in advance helps you avoid the same fate.
- Skipping the contingency. This is the single biggest mistake. Without a reserve, any surprise becomes a crisis.
- Choosing materials before setting a budget. Falling in love with a $15,000 slab of marble before you know your numbers leads to heartbreak or financial strain.
- Ignoring permit costs. Permits for electrical, plumbing, and structural work can add thousands of dollars. Confirm who is responsible for pulling them.
- Underestimating labor. Labor is often 30 percent or more of the total. If your quote seems too low, ask what labor is included.
- Making changes mid-project. Changes after work begins are expensive. Finalize your design and materials before demolition starts.
Each of these mistakes is avoidable with planning. The contingency is your safety net, but the other habits, such as finalizing decisions early and verifying permit responsibility, reduce the likelihood that you will need to use it.
Adjusting Your Contingency as the Project Evolves
Your contingency is not frozen. As the project moves through phases, you can reassess. After demolition, you will have a clearer picture of what is behind the walls. If no major issues appear, you might feel comfortable reducing the reserve slightly. If problems emerge, you may need to increase it.
Keep a running total of spent and remaining funds. If you started with a 20 percent contingency and have used only 5 percent by the halfway point, you are in good shape. If you have used 15 percent before the cabinets are even installed, you need to have a frank conversation with your contractor about scope and expectations.
This flexibility is what makes a contingency realistic. It is not a static number; it is a living part of your budget that responds to reality. Homeowners who treat it as a dynamic tool are far more likely to finish their remodel on solid financial ground.
Financing the Project Without Overextending
Most homeowners do not have the full cost of a kitchen remodel sitting in a savings account. Financing is a common and reasonable option, but it must be managed carefully. Explore home equity loans, personal loans, and contractor financing, and compare interest rates and terms. Avoid putting the entire project on high-interest credit cards if possible.
When you finance, include the contingency in the amount you borrow. It is better to borrow a little more than you need and repay it than to find yourself short and forced into a high-interest emergency loan. Lenders often ask for a detailed budget, so having your numbers organized will speed the approval process.
Remember that the goal is a kitchen you love, not a debt burden you resent. A realistic budget with a healthy contingency is the best way to achieve both. By planning for the unexpected, you give yourself the freedom to enjoy the transformation rather than worry about the next bill.
Start by getting multiple estimates, build your budget from the bottom up, and protect it with a contingency that matches your home's risk profile. Track every expense, communicate openly, and adjust as you go. With that approach, your kitchen remodel becomes a rewarding investment rather than a financial stress test.