Home Equity Loan vs HELOC for Renovation: Which Wins?
Compare home equity loan vs HELOC for renovation to find the right fit. A fixed-rate lump sum offers predictable payments for your remodel.
By Oliver Grant
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
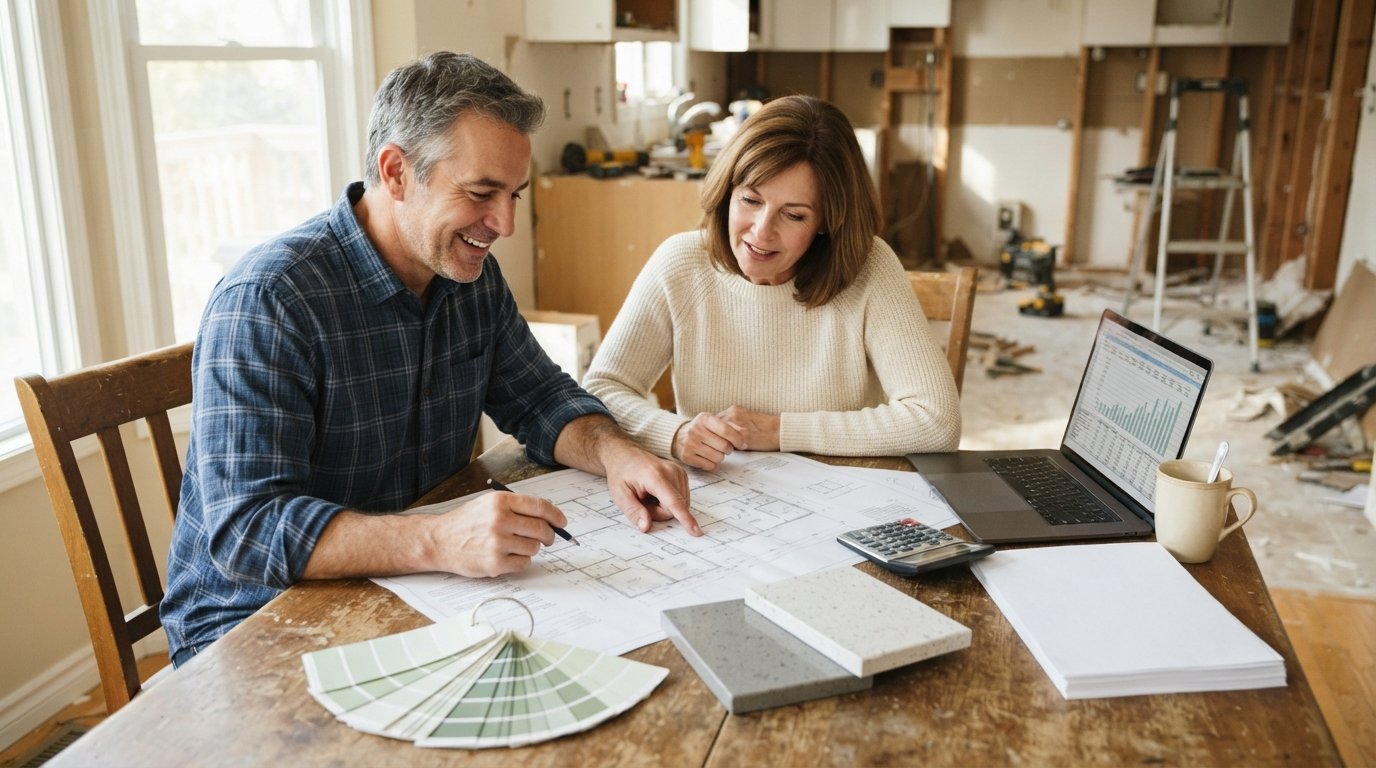
You have finally decided to tackle that kitchen remodel or finally finish the basement. You have picked out the quartz countertops, the perfect shade of sage green for the cabinets, and the flooring that will make the space feel brand new. Then you look at the estimates, and the number staring back at you is higher than what is sitting in your savings account. This is the moment when most homeowners start exploring financing options, and two acronyms almost always dominate the conversation: home equity loans and HELOCs. Understanding the difference between a home equity loan vs HELOC for renovation is the single most important step in making sure your project gets funded without turning your financial life upside down.
Both options let you tap into the value you have built up in your home, but they behave very differently once the money hits your account. One is a lump sum with a fixed rate, the other is a flexible line of credit that you can draw from as needed. Choosing the wrong one for your specific project can mean paying interest on money you are not using, or running out of funds halfway through demolition. This guide breaks down exactly how each option works, when one makes more sense than the other, and how to align your financing with the reality of construction timelines.
How a Home Equity Loan Works for Renovations
A home equity loan is often called a second mortgage, and for good reason. It is a standalone loan that is secured against the equity you have in your home. When you take out a home equity loan, you receive a single lump sum of cash upfront. You then repay that amount over a fixed term, usually between five and thirty years, with a fixed interest rate. This predictability is the defining feature of a home equity loan, and it is what makes it attractive for homeowners who need to know exactly what their monthly payment will be.
For a renovation, this structure works well when you have a clearly defined scope of work and a contractor who has given you a firm bid. If your kitchen remodel is quoted at $45,000 and you have locked in that price, taking out a home equity loan for that exact amount means you can pay your contractor in stages without worrying about fluctuating interest rates. You know from day one what the loan costs you each month, which makes it easier to fit into your household budget alongside your primary mortgage.
However, there is a catch that surprises some homeowners. Because you receive the full amount upfront, you start paying interest on the entire sum immediately, even if your contractor does not need the first draw for a few weeks. If your project has a slow start or involves ordering custom materials with long lead times, you might be paying interest on money that is sitting in your checking account doing nothing. For projects with a tight, predictable timeline, this is a minor issue. For projects with a lot of unknowns, it can be a frustrating inefficiency.
Another consideration is the closing process. Home equity loans typically involve appraisals, title searches, and closing costs that can run between 2% and 5% of the loan amount. These costs are not always obvious when you first start comparing rates. A $50,000 loan could come with $1,500 to $2,500 in fees, which effectively reduces the amount you have available for the renovation itself. It is essential to factor these costs into your overall budget before you commit.
How a HELOC Works for Renovations
A home equity line of credit, or HELOC, operates more like a credit card than a traditional loan. You are approved for a maximum credit limit, and you can draw from that limit as needed during what is called the draw period, which typically lasts five to ten years. During the draw period, you only pay interest on the amount you have actually borrowed, not the full limit. This flexibility is the primary advantage of a HELOC for renovation projects that have uncertain costs or multiple phases.
Imagine you are renovating a bathroom and you discover hidden water damage behind the tile once demolition begins. With a home equity loan, you would need to apply for additional financing or dip into savings to cover the surprise repair. With a HELOC, you simply draw more from your available credit line, provided you have not maxed it out. This ability to adapt to changing circumstances is invaluable in older homes where surprises are the norm rather than the exception.
The interest rate on a HELOC is usually variable, meaning it moves up and down with the prime rate. This introduces an element of uncertainty. Your monthly payment during the draw period might be manageable when rates are low, but it could increase significantly if rates rise. Some lenders offer fixed-rate options for specific draws, allowing you to lock in a rate for a portion of your balance, but this varies by lender and adds complexity to the comparison.
After the draw period ends, the HELOC enters the repayment period. At this point, you can no longer borrow, and you must repay the outstanding balance plus interest over a set term, often ten to twenty years. This transition can cause payment shock for homeowners who were only paying interest during the draw period and suddenly face a fully amortized payment. Planning for this shift is critical if you choose a HELOC.
Key Differences Side by Side
To make a smart decision, it helps to see the two options compared across the factors that matter most for a renovation. The table below summarizes the core distinctions, but the real value comes from understanding how these differences play out in practice.
- Disbursement: Home equity loan gives you a lump sum; HELOC lets you draw funds as needed.
- Interest Rate: Home equity loan is typically fixed; HELOC is usually variable.
- Monthly Payment: Home equity loan is stable and predictable; HELOC payments fluctuate based on balance and rate.
- Closing Costs: Home equity loan often has higher upfront costs; HELOC may have lower or no closing costs.
- Best For: Home equity loan suits fixed-scope projects; HELOC suits phased or uncertain projects.
The lump sum versus draw-as-needed distinction is the most consequential for renovations. Construction projects rarely proceed in a perfectly linear fashion. Your contractor might need a deposit for materials, then a payment after framing, then another after rough-in plumbing and electrical. A HELOC aligns naturally with this payment schedule because you only borrow what you need when you need it. A home equity loan requires you to manage the lump sum carefully, ensuring you have enough to cover each stage without running short.
Interest rate risk is the second major differentiator. If you are risk-averse and value knowing exactly what you will owe each month, a fixed-rate home equity loan provides peace of mind. If you are comfortable with some variability and want to minimize interest costs by borrowing only what you need, a HELOC might save you money over the life of the project, provided rates do not spike dramatically.
Matching the Loan to Your Renovation Type
The nature of your renovation should heavily influence your choice. A cosmetic refresh with a fixed bid and a reliable contractor is a different financial animal than a full gut remodel of a century-old home. Understanding which category your project falls into will point you toward the right financing tool.
Fixed-scope projects with firm bids are ideal candidates for home equity loans. Examples include replacing a roof, installing new windows, or a kitchen remodel where the design is finalized and the contractor has locked in pricing. In these cases, the total cost is known, the timeline is predictable, and the simplicity of a fixed-rate lump sum is a genuine advantage. You can set up a payment schedule with your contractor that matches the loan disbursement, and you never have to think about interest rates again.
Projects with unknowns or multiple phases are better suited to HELOCs. If you are renovating a basement and are not sure whether you will find moisture issues, or if you plan to remodel one room now and another next year, a HELOC gives you the flexibility to borrow incrementally. You can draw funds for the first phase, repay some of the balance, and then draw again for the second phase without reapplying. This is particularly useful for homeowners who are tackling a whole-house renovation in stages to manage disruption and cash flow.
Consider also the timeline of your project. If your renovation will take six months, a HELOC might be more efficient because you are not paying interest on the full amount for the entire duration. If the project will be completed in a few weeks, the interest savings from a HELOC are negligible, and the predictability of a home equity loan becomes more appealing. The longer and more complex the project, the more a HELOC's flexibility is worth.
For homeowners who are planning a comprehensive renovation and want to ensure they are hiring the right professionals for each stage, our guide on complete home renovation planning offers a step-by-step framework that pairs well with any financing choice.
Qualification Requirements and How to Prepare
Whether you choose a home equity loan or a HELOC, you will need to meet similar qualification criteria. Lenders want to see that you have sufficient equity, a solid credit score, and a manageable debt-to-income ratio. Understanding these requirements before you apply can save you time and improve your chances of approval.
Most lenders require you to have at least 15% to 20% equity in your home after accounting for the new loan. If your home is worth $400,000 and you owe $250,000, you have $150,000 in equity. A lender might allow you to borrow up to 80% or 85% of your home's value, which in this case would be $340,000. Subtracting your existing mortgage balance of $250,000 leaves you with a maximum borrowing capacity of $90,000. This calculation is the starting point for any home equity financing.
Your credit score will determine the interest rate you are offered and, in some cases, whether you qualify at all. Generally, a score of 700 or higher secures the best rates, while scores below 620 may make it difficult to qualify for favorable terms. If your credit score needs improvement, paying down revolving debt and correcting any errors on your credit report can make a meaningful difference in the rate you receive.
The debt-to-income ratio is another critical factor. Lenders typically want your total monthly debt payments, including the new home equity loan or HELOC payment, to be no more than 43% of your gross monthly income. If you are close to that threshold, paying off a car loan or reducing credit card balances before applying can help you qualify for a larger amount or a better rate.
Risks and Smart Borrowing Strategies
Using your home as collateral for a renovation loan carries inherent risk. If you fall behind on payments, the lender can foreclose, putting your home at risk. This is not a reason to avoid home equity financing altogether, but it is a reason to borrow conservatively and have a clear repayment plan.
One of the biggest mistakes homeowners make is borrowing the maximum amount they qualify for rather than the amount they actually need. Just because a lender approves you for $80,000 does not mean you should borrow $80,000 for a project that costs $50,000. Borrowing only what you need reduces your monthly payment and minimizes the interest you pay over time. It also leaves room in your credit line for emergencies or future projects.
Another smart strategy is to maintain an emergency fund alongside your renovation budget. Renovations almost always encounter unexpected costs, whether it is a permit fee you did not anticipate or a material price increase. Having a cash buffer means you can handle these surprises without maxing out your HELOC or scrambling for additional financing. Aim to set aside 10% to 20% of your project budget for contingencies.
Finally, be cautious about variable rates. If you choose a HELOC and the rate is variable, stress-test your budget to see if you can still afford the payments if the rate rises by two or three percentage points. If the answer is no, a fixed-rate home equity loan might be the safer choice, even if the initial rate is slightly higher. When it comes to financing your home, predictability often outweighs the potential for short-term savings.
Tax Implications and Documentation
The interest on home equity loans and HELOCs used for home improvements may be tax-deductible, but the rules are specific. Under current tax law, the interest is deductible only if the funds are used to buy, build, or substantially improve the home that secures the loan. Renovations that qualify include adding a new room, replacing a roof, or upgrading HVAC systems. Using the funds to pay off credit card debt or take a vacation does not qualify.
To claim the deduction, you must itemize your deductions and be able to show that the loan proceeds were used for qualifying improvements. Keeping detailed records of your renovation expenses and the loan disbursements is essential. Consult a tax professional to understand how the rules apply to your specific situation, as tax laws can change and individual circumstances vary.
From a documentation perspective, both loan types require proof of income, employment verification, and details about your existing mortgage. Having these documents ready before you apply can streamline the process. Some lenders also require a home appraisal to confirm the property's value, which adds time and cost to the application process. Understanding these requirements upfront helps you set realistic expectations for how quickly you can access funds and start your renovation.
Making the Final Decision
Choosing between a home equity loan and a HELOC for your renovation comes down to three factors: the certainty of your project costs, your tolerance for interest rate variability, and your preference for payment predictability. If your project has a fixed scope and a firm bid, a home equity loan offers simplicity and stability. If your project is phased, uncertain, or likely to evolve, a HELOC provides the flexibility to adapt without reapplying for new financing.
Many homeowners find that a hybrid approach works well. They take out a home equity loan for the known, fixed costs of the project and establish a small HELOC as a backup for unexpected expenses. This strategy combines the predictability of a fixed-rate loan with the flexibility of a credit line, giving you the best of both worlds without over-borrowing.
Whichever option you choose, the goal is to fund your renovation in a way that enhances your home without compromising your financial stability. A well-planned renovation can increase your property value, improve your quality of life, and make your home a better fit for your needs. The financing is simply the tool that makes it possible. By understanding the differences between a home equity loan and a HELOC, you can choose the tool that matches your project and your peace of mind.
Before you sign any loan documents, take the time to get multiple estimates from contractors and compare financing offers from at least two or three lenders. The combination of the right project plan and the right financing can turn a stressful renovation into a rewarding investment in your home. HomeRemodelingsContractors