Government Grants and Low Interest Loans for Home Repairs
Government grants and low interest loans for home repairs can cover roofs, furnaces, and accessibility fixes. Call 8333658755 to explore your options.
By Zoe Harper
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Your roof is leaking, your furnace is on its last legs, or your home needs accessibility modifications you cannot afford upfront. The repair bill feels impossible, but walking away is not an option. What most homeowners do not realize is that federal, state, and local programs exist specifically to help people in exactly this situation. Government grants and low interest loans for home repairs are not urban legends. They are real funding tools, and millions of dollars go unclaimed every year because eligible homeowners simply do not know where to look or how to apply.
This guide breaks down how these programs work, who qualifies, what the money can cover, and how to navigate the application process without wasting weeks on dead ends. Whether you are a senior on a fixed income, a veteran, a rural homeowner, or someone recovering from a natural disaster, there is likely a program designed with you in mind. The key is understanding the landscape and knowing which doors to knock on first.
What Are Government Grants and Low Interest Loans for Home Repairs?
The phrase covers a wide range of financial assistance programs funded by federal agencies, state housing authorities, and local municipalities. The common thread is that they exist to help homeowners maintain safe, livable, and energy-efficient housing, often when private financing is out of reach or would create financial hardship.
A grant is money you do not repay. It is typically reserved for specific populations (seniors, veterans, disabled homeowners, low-income households) or specific purposes (lead paint removal, accessibility ramps, emergency repairs). A low interest loan, by contrast, must be repaid, but the terms are far more forgiving than anything a bank would offer: interest rates as low as 1 percent, deferred payments, or even forgiveness after a set number of years if you remain in the home.
Some programs blend the two. For example, you might receive a loan with a portion forgiven each year you stay in the property. Others operate as matching grants, where the government covers a percentage of the cost and you cover the rest. Understanding which category a program falls into matters because it affects your long-term financial obligation.
The funding sources vary just as widely. At the federal level, the Department of Housing and Urban Development (HUD), the Department of Agriculture (USDA), the Department of Veterans Affairs (VA), and the Department of Energy all operate repair-related programs. States often layer their own initiatives on top, and local governments use Community Development Block Grants (CDBG) and HOME funds to run hyper-local repair programs. The result is a patchwork that can feel overwhelming, but also means there is likely something available in your area.
Who Qualifies for Home Repair Assistance?
Eligibility rules differ from program to program, but most fall into a few recognizable patterns. Income limits are almost always part of the equation. Federal programs typically tie eligibility to area median income (AMI), with many set at 80 percent or below. Some emergency programs go higher, especially after a declared disaster.
Beyond income, certain groups receive priority or exclusive access. Seniors aged 62 and older are the focus of several HUD and USDA programs. Veterans may qualify for VA-backed loans or grants for accessibility modifications. Homeowners with disabilities often find dedicated funding for ramps, widened doorways, and bathroom modifications. Rural residents have access to USDA programs that urban homeowners cannot use.
Property condition and location also matter. Some programs require the home to be your primary residence. Others cap the value of the home or restrict funding to specific neighborhoods, often those designated as blighted or historically underserved. If you live in a floodplain or a designated disaster area, additional programs may open up.
Here is a quick reference for the most common eligibility factors:
- Household income at or below 80 percent of area median income (some programs allow up to 100 percent or higher)
- Property must be your primary residence, not a rental or investment property
- Specific status such as senior, veteran, disabled, or rural resident
- Home must need repairs that meet program guidelines (health, safety, accessibility, energy efficiency)
- Current on property taxes and mortgage payments (varies by program)
One important caveat: even if you meet every stated criterion, funding is finite. Most programs operate on a first-come, first-served basis or through waiting lists that can stretch months or even years. Applying early and to multiple programs simultaneously improves your odds of securing assistance before a small problem becomes a catastrophic one.
Federal Programs You Should Know About
The federal government is the largest single source of home repair funding, though it rarely writes checks directly to homeowners. Instead, it channels money through state and local agencies, which then administer the programs. Knowing the federal programs helps you understand what might be available through your local housing office.
HUD and Community Development Block Grants
HUD does not offer direct grants to individual homeowners, but it funds the CDBG program, which allocates money to states and cities for housing rehabilitation. These funds often flow to local nonprofits and housing authorities that run repair programs for low-income homeowners. Typical uses include roof replacement, heating system repair, plumbing upgrades, and accessibility modifications. To access these funds, you generally apply through your city or county housing department.
The HOME Investment Partnerships Program is another HUD initiative that supports affordable housing, including owner-occupied rehabilitation. Like CDBG, it operates through local agencies. The advantage of these programs is that they often come with deferred payment loans, meaning you pay nothing until you sell or transfer the home.
USDA Section 504 and Section 502 Loans
If you live in a rural area, the USDA offers two powerful tools. Section 504 Repair Loans and Grants provide up to $40,000 in loans and up to $10,000 in grants (as of 2026) to very low-income homeowners aged 62 or older. The funds can be used for repairs that remove health and safety hazards, such as fixing a leaking roof, installing a ramp, or repairing a broken furnace.
Section 502 loans are for rural homeowners who need to repair or improve their homes but cannot obtain credit elsewhere. These are low interest loans with terms up to 20 years. The USDA defines rural broadly, so many suburban and exurban areas qualify. Checking the USDA eligibility map is a worthwhile first step if you are outside a major city.
VA Home Repair Grants and Loans
Veterans have access to several options. The VA offers Specially Adapted Housing (SAH) grants for severely disabled veterans to modify their homes for accessibility. The Special Housing Adaptation (SHA) grant serves veterans with certain service-connected disabilities. These grants can cover major modifications like roll-in showers, widened doorways, and exterior ramps.
For non-disability-related repairs, the VA backs low interest loans through private lenders, often with no down payment. Veterans should contact their regional VA office or a VA-approved lender to explore options. The key is that these benefits are earned, not charity, and many veterans underuse them.
Department of Energy Weatherization Assistance Program
The Weatherization Assistance Program (WAP) focuses on energy efficiency improvements for low-income households. It can cover insulation, air sealing, furnace repair or replacement, and sometimes minor health and safety repairs. The program is administered through state and local agencies. While it will not fix a collapsing roof, it can significantly reduce energy bills and improve indoor air quality, which is often a first step toward broader repairs.
These federal programs rarely advertise. You have to seek them out. A good starting point is your state housing finance agency or a local HUD-approved housing counseling agency. They can tell you which programs are active in your area and help you prepare an application.
State and Local Programs: The Hidden Goldmine
While federal programs get the headlines, state and local governments often run more accessible and flexible repair programs. These are funded through a mix of federal pass-through dollars, state appropriations, and local bonds. Because they are closer to the ground, they can respond to specific local needs, such as hurricane retrofits in coastal areas or lead abatement in older cities.
Examples include:
- State housing finance agencies offering below-market rate loans for essential repairs
- County programs for emergency repairs, such as furnace replacement in winter or roof patching after a storm
- City-run programs for lead paint removal, often targeting homes built before 1978
- Nonprofit housing organizations that administer repair funds with volunteer labor to stretch dollars further
The challenge is discovering what exists. A good strategy is to call your local city or county housing department and ask specifically about homeowner repair programs. If they do not have one, ask which agency does. In many regions, the local Area Agency on Aging is a hub for senior repair programs, while Community Action Agencies handle weatherization and emergency assistance.
Another often-overlooked resource is your state's housing finance agency. These quasi-governmental organizations issue bonds and use the proceeds to fund low interest loan programs. Some offer repair loans at 2 to 3 percent interest with no closing costs. The application process is typically simpler than a bank loan, though income limits apply.
How to Apply for Government Grants and Low Interest Loans for Home Repairs
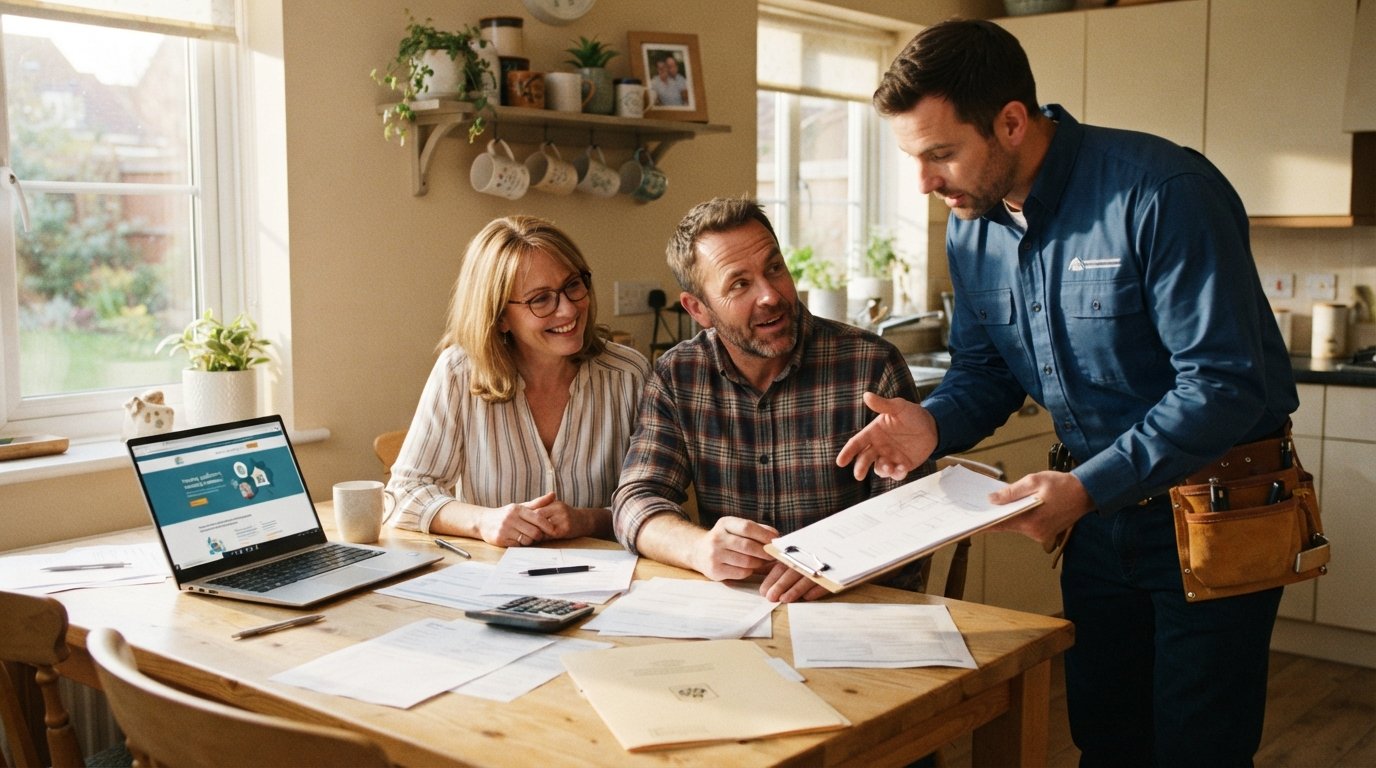
The application process can feel bureaucratic, but it is manageable if you approach it systematically. Most programs require documentation of income, assets, property ownership, and the nature of the needed repairs. Missing paperwork is the most common reason applications stall, so gathering everything upfront saves weeks.
Here is a step-by-step framework that works for most programs:
- Identify your goal. Are you fixing a health hazard, making accessibility modifications, or improving energy efficiency? Different goals lead to different programs.
- Research programs. Start with your local housing department, then check state housing finance agency websites and federal program portals. Our guide on how to get a government grant for home repairs walks through the research phase in more detail.
- Gather documents. You will likely need proof of income (tax returns, pay stubs), proof of homeownership (deed, mortgage statement), photo ID, and possibly a repair estimate from a licensed contractor.
- Submit applications to multiple programs. Do not wait for one to reject you before applying to another. Funding is limited, and processing takes time.
- Follow up. Government offices are busy. A polite phone call every two weeks can keep your application moving and surface any missing items.
One practical tip: many programs require a contractor estimate before they will approve funding. This means you need to find a qualified contractor early in the process. Platforms like HomeRemodelingsContractors.com help homeowners connect with experienced local contractors who can provide the detailed estimates these programs require. Having a contractor lined up also demonstrates to the program that you are serious and ready to proceed once funds are released.
Be prepared for inspections. Most programs send an inspector to verify the needed repairs and ensure the work meets code. This is not a hurdle to fear; it protects you from shoddy work and ensures the funds are used appropriately. Once approved, the program typically pays the contractor directly, so you are not fronting the money and waiting for reimbursement.
Common Pitfalls and How to Avoid Them
The biggest mistake homeowners make is assuming they will not qualify. Income limits are often higher than people expect, and some programs have flexibility for special circumstances. Applying costs nothing but time, and the potential payoff is significant.
Another pitfall is falling for scams. Legitimate government programs do not charge application fees, do not demand upfront payments, and do not guarantee approval. If someone offers to "secure your grant" for a fee, walk away. The same goes for contractors who pressure you to sign immediately or ask for large deposits before work begins. Government programs have safeguards, but you still need to do your due diligence.
A third issue is scope creep. You may start applying for a roof repair grant and discover you also need plumbing work. Some programs allow multiple repairs under one application, but others are narrowly focused. Read the guidelines carefully and, if needed, submit separate applications for separate issues. Trying to bundle unrelated repairs into one application can lead to rejection.
Finally, do not overlook the importance of maintaining your property after repairs are complete. Some loans are forgivable only if you remain in the home for a set period, often five to ten years. Selling or refinancing too soon could trigger repayment. Understand the terms before you sign.
Building a Realistic Funding Strategy
Government grants and low interest loans for home repairs are powerful tools, but they are rarely a complete solution on their own. Most programs cap assistance at a certain amount, and the most generous grants are reserved for the lowest-income households or those with specific statuses like veteran or senior.
A realistic strategy often combines several sources. You might use a USDA Section 504 grant for a new roof, a state low interest loan for a furnace replacement, and your own savings for cosmetic repairs. Or you might use a deferred payment loan that requires no monthly payments, preserving your cash flow for other necessities. The key is to think of these programs as building blocks, not lottery tickets.
It also helps to prioritize repairs that affect health and safety first. A leaking roof or a broken furnace is more urgent than outdated kitchen cabinets. Many programs are designed around this hierarchy, so aligning your request with their priorities improves your chances. If you are planning a larger renovation and want to understand how to phase it affordably, connecting with a contractor who understands government programs can be invaluable. You can start by requesting free estimates from local pros who are familiar with the paperwork and inspection requirements.
Finally, keep records of everything: applications, correspondence, inspection reports, and receipts. If you are audited or need to prove compliance with program rules, having a paper trail protects you. It also makes future applications easier, since you will already have the documentation ready.
The bottom line is that help exists, but it does not come looking for you. With a bit of research and persistence, you can turn a daunting repair bill into a manageable project. Start with your local housing office, gather your documents, and apply broadly. The worst that can happen is a rejection letter; the best is a safer, more comfortable home without a crushing financial burden.